Strategy
After Hurricane Beryl: what to check in a property and in your hurricane insurance
Beryl made landfall north of Tulum as a Category 2. What to check in the construction and the insurance before buying on the coast.
For whom
Anyone buying a house or condo on the Quintana Roo coast, to live in or to rent.
On July 5, at 5:05 in the morning, Hurricane Beryl made landfall north of Tulum as a Category 2, with sustained winds of 175 kilometers per hour and gusts of 220. In Quintana Roo nobody died or was injured. There were fallen trees, poles and roofs, mostly in Tulum, where the power company reported 40% of the population without electricity, and 2,193 people spent the night in 58 shelters.
For anyone buying on the coast, Beryl was a reminder: hurricane season is part of living here. What you can choose is how the property is built and how it is insured.
What to check in the building
- Windows and frames. Ask whether the glass is tempered or laminated and what wind load the frames are designed for.
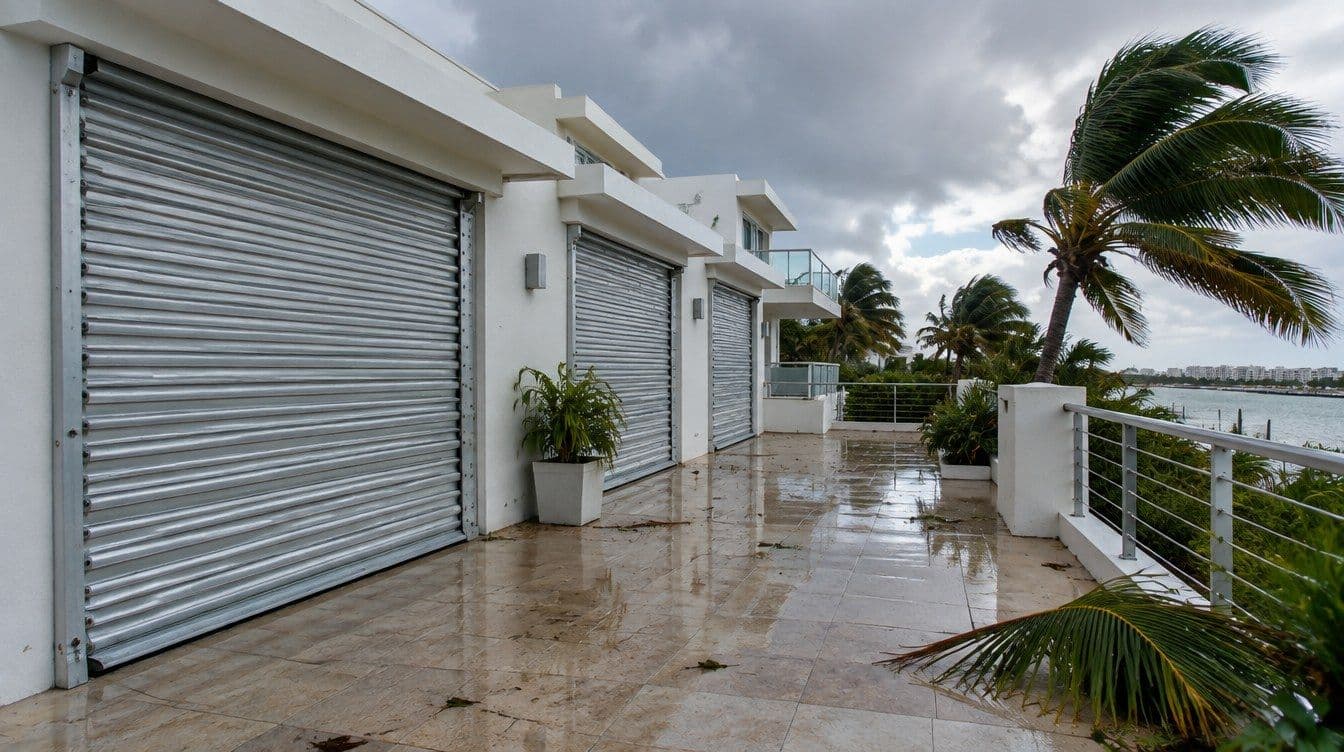
- Protection. If the building has hurricane shutters, who closes them and how far in advance.
- Roof and drainage. Check the waterproofing and the rainwater downspouts before the season.
- Trees and utility poles near the building.
- Backup power and water storage. After Beryl some areas had no electricity and water cuts; a building with an emergency generator and a cistern gets through those days better.
- Height and location. A ground-floor unit on the beach does not ride out a storm the same way as a third-floor unit one block back.
What to check in the insurance
- Mexico's financial consumer agency, Condusef, explains that hydrometeorological coverage is not regularly included in home insurance, but it can be added. Ask for a policy that names it explicitly.
- Review the deductible, coinsurance and exclusions before signing, not after the storm. In higher-risk areas, premiums and deductibles tend to be higher.
- Declare the real construction value. If you declare it low, you pay a lower premium, but you also get paid less if something happens.
- In a condo, ask what the building's policy covers and what you need to insure yourself.
- Mexico has 8 million insured homes, but only 7% were insured voluntarily; almost all the rest have insurance because a mortgage required it. If you buy with cash, nobody will force you to insure. It is on you.
Our take
We have been on this coast for 19 years and have been through several strong seasons. A hurricane does not make us rule out the coast. It makes us ask about the construction, the insurance and the condo's reserve fund before we talk about price.
If you are about to buy, ask for the building's policy and your own. If you like, we will review them with you.
Sources
- Proceso, July 5, 2024: Beryl makes landfall in Tulum as a Category 2 hurricane (in Spanish)
- El Informador, July 5, 2024: damage from Hurricane Beryl in Quintana Roo (in Spanish)
- Condusef, Proteja su Dinero magazine: protect your home from hydrometeorological events (in Spanish)
- El Financiero, July 20, 2024: how home insurance works (in Spanish)